
 GMA Brandtalk
 Tracking
 Archives

GLOBAL MARKETS: Oil prices ease as exports increase
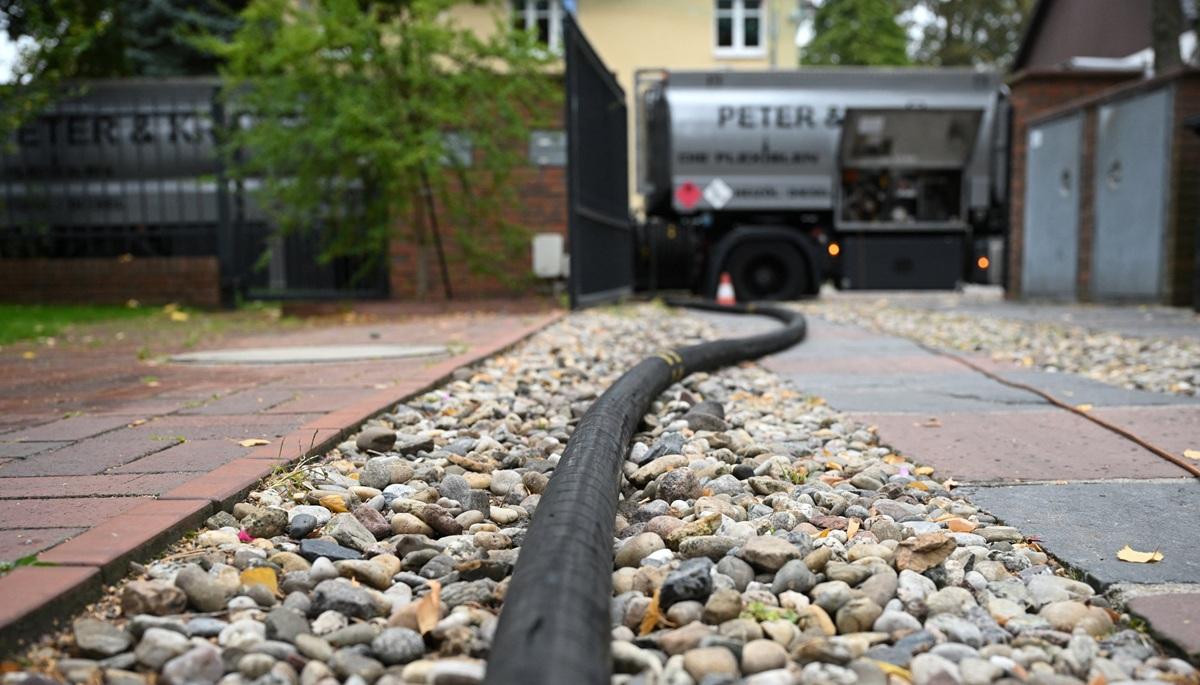
Oil prices fell on Monday after crude exports from the Middle East increased and the Group of Seven nations pledged to boost supplies, though selling was limited by ongoing disruption fears linked to the US-Israeli war on Iran.
Brent crude futures dropped 0.44% to $101.78 a barrel, while US crude was down about 0.5% at $90.68.
United States equities were buoyed by advances in megacap and growth stocks on Monday, as Treasury yields held near multi-year highs, the dollar advanced against the euro, and oil prices relented.
On Wall Street, indexes were supported by heavyweight technology stocks such as Nvidia
Concerns over France's fiscal position pushed the euro to a 17-month low and weighed on French assets. Europe's pan-regional STOXX 600 index edged up 0.2%, although Paris shares fell about 1% to six-month lows.
Brazilian stocks the real rallied after right-wing Senator Flavio Bolsonaro outperformed poll predictions in the first round of the presidential election and advanced to a runoff against leftist incumbent Luiz Inacio Lula da Silva.
MSCI's gauge of stocks across the globe rose 0.56%.
"Relative equity market calm amid the bond market’s 'perfect storm' is understandable, given accelerating economic growth and the AI boom’s rate insensitivity," Lisa Shalett, chief investment officer of Morgan Stanley Wealth Management, said in an email Monday.
Shalett wrote that her team was watching three areas for signs of stress: equity market and earnings revisions breadth; high-yield bond spreads; and US dollar strength along with currency market volatility.
France weighs on the Euro
The euro recovered some ground to trade at $1.121 after falling by as much as 0.8% to a 17-month low of $1.1160.
The single currency, down about 2.5% last month, has come under pressure as investors fret over France's rising debt and political gridlock ahead of next year's presidential election.
The premium investors demand to hold French 10-year bonds over safer German debt surged above 150 basis points on Friday, fueling concerns of broader contagion across European markets.
"France is the real deal in terms of risk premia for the euro," said Saxo strategist Neil Wilson, noting that French government plans to reduce the budget deficit still face parliamentary scrutiny and could ultimately be watered down.
French 10-year yields stayed below Friday's peak of 4.993%, while German yields were also little changed.
The euro's slide lent fresh support to the dollar, which also drew strength from elevated Treasury yields. The dollar index rose 0.25%.
While expectations of a Fed pause could weigh on the dollar, "US growth outperformance and strong foreign appetite for US securities keep US dollar risks skewed to the upside," said Elias Haddad, global head of markets strategy at BBH.
Benchmark 10-year US Treasury yields jumped 4.68 basis points to 5.32%, as borrowing costs across major economies remain near multi-year highs as deteriorating public finances, heavy debt issuance and elevated energy prices continue to pressure bond markets.
Fed repricing offers support
Trading was thin in Asia due to holidays in China and South Korea as well as in Australia's New South Wales state, though regional markets took their cue from Wall Street's gains on Friday after weaker-than-expected US labor data.
Figures released last week showed US job growth slowed more than expected in September and payrolls for the previous two months were revised sharply lower, prompting investors to largely rule out a Federal Reserve rate increase this month.
Japan's Nikkei rose 2.4% and MSCI's broadest index of Asia-Pacific shares outside Japan rose 1.3%.
Investors now see an 18% chance of a Fed rate increase this month, down from 64% a week ago, according to CME FedWatch data, though a move in December remains largely priced in.
Spot gold was little changed at $4,137 an ounce. — Reuters

